An AI voice agent may be used for collections calls in South Africa when the deployment is designed around POPIA, the National Credit Act, applicable debt collection rules and the credit provider’s own legal requirements. In practice that means the agent operates on a confirmed lawful basis, discloses nothing until the customer’s identity is confirmed, offers only approved arrangements, and follows the credit provider’s configured rules for disclosure, disputes and escalation. Those controls are not add-ons. They are the design.
This guide sets out what each framework shapes, what the agent has to do on every call, and the questions to put to any vendor. It is written for collections, compliance and legal leaders at South African credit providers. It is general information, not legal advice, and every credit provider should apply it to its own portfolio and processes.
Why collections is where the legal question gets asked first
A collections call discloses personal financial information, negotiates money and has a regulator attached to every step. It is also the call South Africans dread most. TransUnion’s Q2 2026 Consumer Pulse found 39% of consumers expect to miss at least one bill or loan repayment. Experian’s Q1 2026 Consumer Default Index has retail loan defaults up 11% year-on-year to 17.18%.
So the volume is there and the sensitivity is there. Legal teams are right to ask the question before anything goes live. The answer depends on three frameworks.
What POPIA requires of an AI voice agent on a collections call
The Protection of Personal Information Act governs how the customer’s information is processed during the call. The agent does not create a new basis for processing. It has to operate inside a lawful basis and purpose the credit provider has already confirmed for that portfolio and that processing activity.
In practice that means four things:
- Lawful basis and purpose. The credit provider confirms the basis on which it contacts each segment of the book, and the agent processes only what that purpose needs.
- Minimality. The agent asks for identity confirmation and what the customer can manage. It does not collect anything else.
- Identity before disclosure. Reading a balance to the wrong person is a breach. The agent confirms it is speaking to the account holder before it discloses anything.
- The vendor as operator. The business deploying the agent remains the responsible party. The vendor is an operator, and the contract, security safeguards and retention rules must reflect that.
A compliant AI voice agent processes only the information needed to administer the credit agreement, and discloses nothing until identity is confirmed.
What the National Credit Act adds
The National Credit Act governs the relationship between the credit provider and the consumer, including how default is handled. Two points matter for an AI voice agent.
First, the agent is a channel for collections communication. It is not a substitute for the statutory notices the Act requires before enforcement. Those stay exactly as they are.
Second, the Act and the regulator’s conduct expectations apply to the agent as they would to a human collector. No misleading statements about consequences, no pressure outside the arrangement options the credit provider has approved, and contact inside the hours and frequency the business has set. Where a customer indicates they are under debt review or have legal representation, the call has to move to a person.
An AI voice agent does not change what the National Credit Act requires. It makes compliance with it consistent on every call.
The Debt Collectors Act and third party collectors
Where collections are outsourced, the Debt Collectors Act and the Council for Debt Collectors’ code of conduct apply to the registered collector. An AI voice agent deployed by that collector operates inside the same conduct framework: it states which business it is calling for, follows the approved disclosure script, avoids intimidation and misrepresentation, and contacts customers within the configured hours.
The practical consequence is that the agent’s configuration has to be written to the code, and the collector has to be able to show that it was.
The six controls a compliant deployment needs
Across all three frameworks, the same six controls come up. If any one is missing, the deployment is not ready.
- Identification and disclosure rules. The agent states which business it is calling for and follows that business’s approved disclosure script.
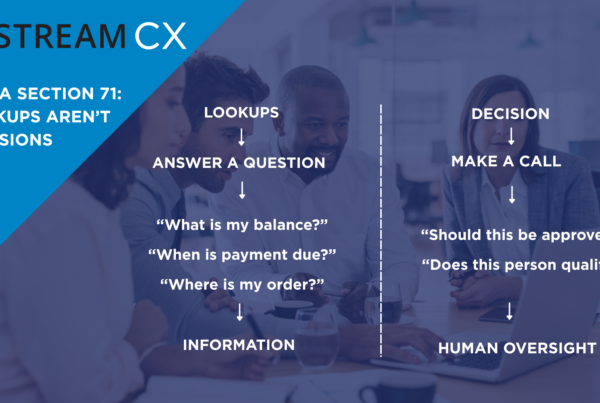
- Identity confirmation before disclosure. No balance, no arrears status, nothing, until the agent has confirmed it is speaking to the right person.
- Lawful basis and contact windows configured. The calling hours and frequency are enforced in the system, not left to judgement.
- Approved arrangements only. The agent can offer what the credit provider has authorised for that segment and nothing else.
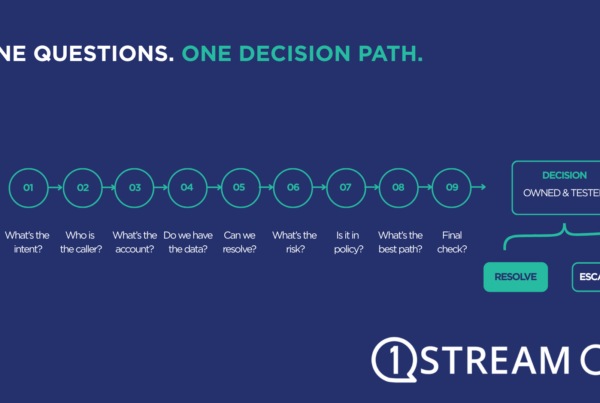
- Dispute and escalation rules. A dispute follows the credit provider’s approved process. Requests for a person, distress, hardship, debt review and legal representation follow their configured outcomes, including transfer where required, with the transcript and data preserved.
- Logging. Every call records identity confirmed, disclosure made, arrangement offered, outcome and next-step reason. Structured and auditable.
Why certification matters here
Controls on paper are a promise. A management system behind them is evidence.
1Stream is certified to ISO/IEC 42001, the international standard for AI management systems. On a collections deployment that means a named owner for the agent’s rules, change control on every script and trigger, testing against recorded scenarios before and after every change, and an audit trail a regulator or a customer can be shown.
Certification does not make a deployment compliant on its own. What it does is give a legal or compliance team specific controls and evidence to assess, which makes their review faster and more concrete.
What it delivers commercially
Compliance is the condition. Coverage is the return.
A human desk works a list from the top down and runs out of hours before it reaches the small balances. An AI voice agent, within the calling windows, concurrency and contact data the business has in place, can reach far more of the book in the first days of the month. The small retail balances a human desk never gets to are the ones that decide whether a book rolls or recovers.
Questions to ask any vendor
What identification and disclosure script does the agent use at call open? It should state which business it is calling for and follow the credit provider’s approved disclosure approach consistently.
What happens when the customer disputes the balance? Ask to see the configured process. The agent may explain the next step, direct the customer to the appropriate channel, or transfer to a person, depending on the credit provider’s rules.
What is logged on every call? Identity confirmation, disclosure, arrangement offered, outcome and handover reason, as structured data.
How is the vendor’s AI management audited? Ask for the standard, not the adjective. 1Stream is certified to ISO/IEC 42001, which covers the management system behind the agent, not the legal status of any individual deployment.
Which languages does it speak? English and Afrikaans today, with more South African languages on the way.
Does it run on one platform? Voice, the AI voice agent, the integration to the credit system, recording and analytics on a single platform means one place to check the data is right. Four vendors means four places, and the customer finds the gap first.
In summary
- An AI voice agent may be used for collections calls in South Africa when the deployment is designed around the applicable rules: it operates on a confirmed lawful basis, confirms identity before disclosure, follows the approved identification and disclosure script, offers only approved arrangements, follows configured dispute and escalation rules, and logs every call.
- POPIA governs the information, the National Credit Act governs the conduct, and the Debt Collectors Act governs third party collectors. None of them gives a simple technology-specific answer. All of them determine how the collections process and its use of personal information have to be designed.
- Certification to ISO/IEC 42001 is what turns the controls into evidence a reviewer can assess.
If you are working out where an AI voice agent fits on your collections book, book a CX AI Readiness Assessment. It is a 45-minute structured conversation that ends with a written recommendation.
This article is general information for collections, compliance and legal leaders. It is not legal advice. Every credit provider should apply it to its own portfolio, processes and legal requirements.
Sources: Eighty20/XDS Credit Stress Report Q1 2026 (eighty20.co.za/credit-stress-report); Experian Consumer Default Index Q1 2026 (reported by Business Day, 17 June 2026); TransUnion Consumer Pulse Q2 2026 (newsroom.transunion.co.za).